Property moves fast.
Your mortgage can too.
Ten years building and renovating property. Now I help buyers and investors reach a mortgage offer without the delays.
Access to hundreds of lenders across the UK
Compare the options and find the mortgage that fits your circumstances.


Lenders available through Mortgage Lane include NatWest, Nationwide, Barclays, Halifax, Santander, HSBC UK, Accord, Coventry, Skipton, Kensington, Precise, Together.
First-time buyers
Deposit, affordability and what happens in what order.
Get started
Remortgaging
Your deal is ending, or you want to borrow more.
Get started
Moving home
Porting, selling and buying, or letting out your current home.
Get started
Buy-to-let
Buying personally or through a limited company.
Get started
Complex cases are welcome, including bridging, development and specialist finance.
Process
The mortgage process, start to finish
Four stages. You will always know which one you are in and what happens next.
- 1
Understanding the case
Everything starts with a proper conversation. I go through your income, your deposit or equity, the property itself and what you are trying to achieve. If it is an investment purchase, that includes rental figures, any refurbishment plans and how the property is being held. Once I have the full picture, I search the market and come back with a recommendation and the reasoning behind it.
- 2
Decision in principle
When you are happy with the recommendation, I put the case to the lender for a decision in principle — usually the same day. This confirms the lender is willing to lend, and on what terms, before anything is committed. In here, you pay an initial fee to process your case. Lender and valuation fees become payable when we move to full application.
- 3
Application, valuation and underwriting
I submit the full application and package the supporting documents so the underwriter has everything in one go — this is where most delays happen, and where preparation earns its money. The lender books the valuation, underwriting runs alongside it, and I chase both. If a query comes back, I deal with it rather than passing it to you.
- 4
Offer to completion
Once the formal offer is issued, your solicitor takes over the legal work. I stay on the case — keeping the lender, solicitor and agent moving, flagging anything that looks like it is drifting, and making sure the offer does not expire while everyone waits on each other. [CLOSING LINE — one sentence on staying in touch after completion, e.g. reviewing the rate before the product ends.]
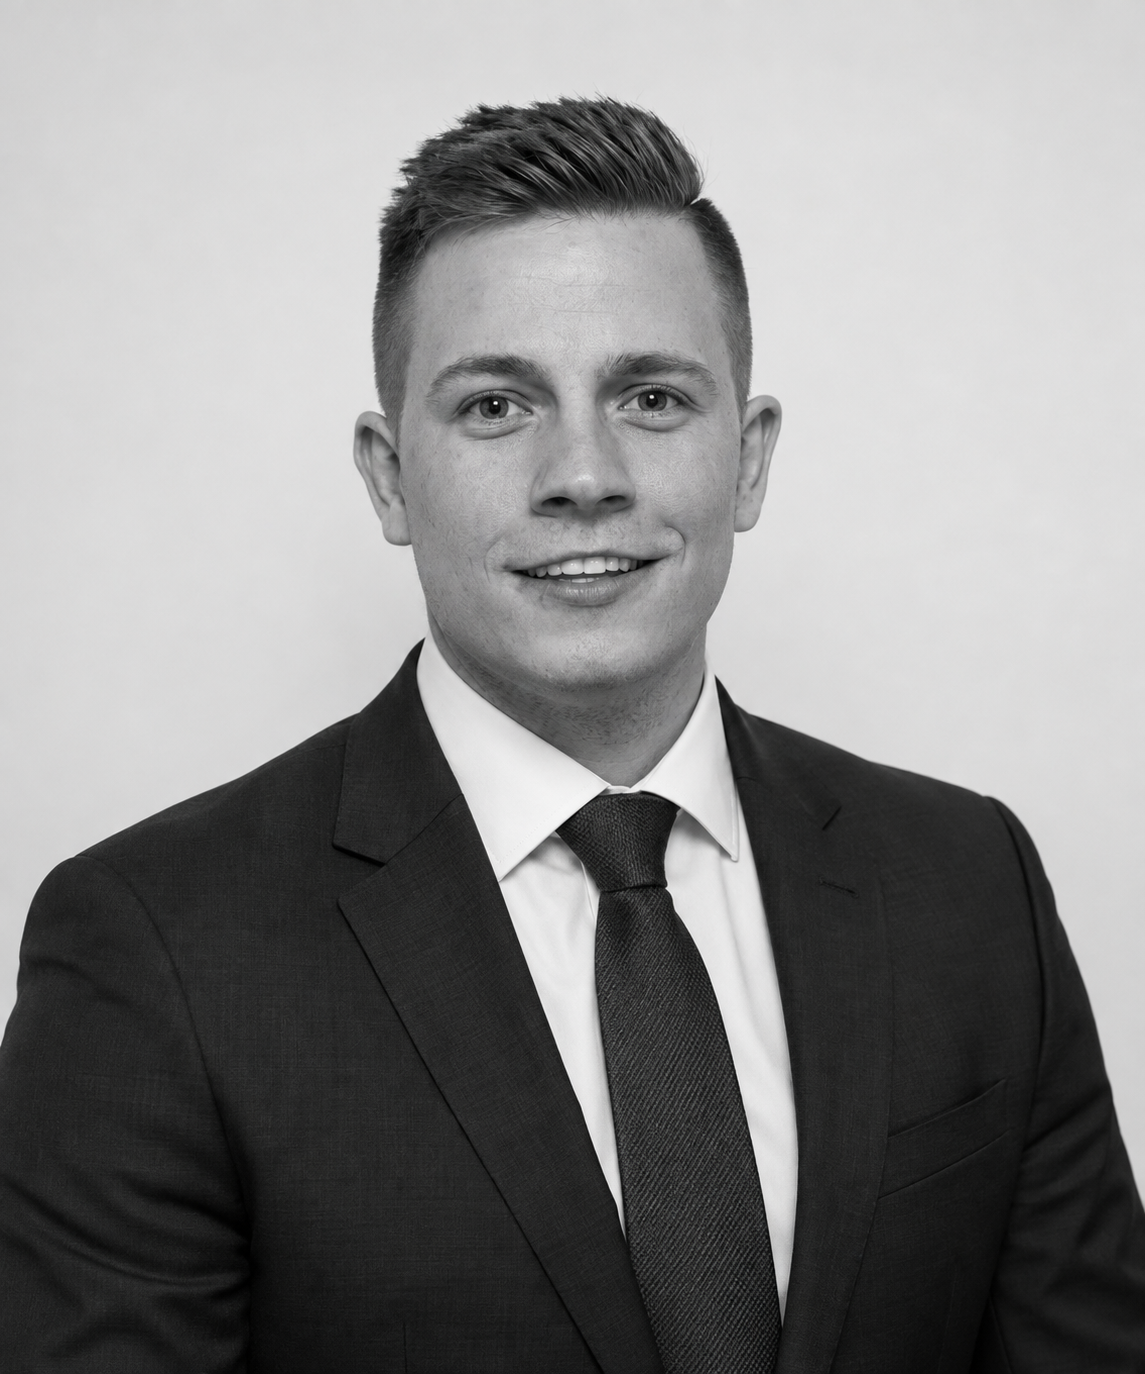
Kristian Toth
Property has been part of my life from a young age, starting with my father and later leading me to build a career in London across construction, renovation, buying and letting.
After years in property, I saw how often finance could slow a deal down, so becoming a mortgage broker felt like the natural next step.
Today, I combine hands-on property experience with mortgage advice, helping clients understand both the finance and the property behind it so they can move quickly, make informed decisions and achieve the best possible outcome.
Rates
Latest mortgage rates
Illustrative examples, updated September 2026.
| Initial rate | Initial payment | Reversion rate | Total fees | Type | APRC | Initial period | Early repayment charge |
|---|---|---|---|---|---|---|---|
| 4.17% | £604.43 | 6.49% | £999.00 | Tracker | 6.23% | 24 months | Yes |
| 4.20% | £606.31 | 6.74% | £20.00 | Tracker | 6.44% | 24 months | No |
| 4.29% | £611.98 | 6.00% | £1,050.00 | Discounted | 5.71% | 36 months | Yes |
| 4.53% | £627.23 | 7.24% | £1,099.00 | Fixed | 6.66% | 39 months | Yes |
| 4.70% | £638.15 | 6.24% | £1,016.00 | Fixed | 5.83% | 61 months | Yes |
The examples in this table are based on a property valued at £150,000 with a £112,500 mortgage secured against it, excluding any additional fees.
Figures assume a capital and interest repayment mortgage over a 25 year term.
These are illustrative examples, not live pricing and not an offer of credit. Rates, fees and criteria change frequently, and the amount you can borrow depends on your own circumstances.
REVIEWS
What my clients say
Sample reviews shown for illustration only. Genuine client reviews will appear here once collected.
Sample review 1
14 August 2026
“Sample review text for illustration only.”
Sample review 2
3 September 2026
“Sample review text for illustration only.”
Sample review 3
21 July 2026
“Sample review text for illustration only.”
Sample review 4
29 August 2026
“Sample review text for illustration only.”